

Acorns: Invest For Your Future
4.7

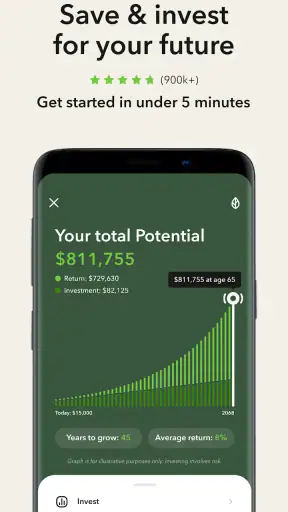
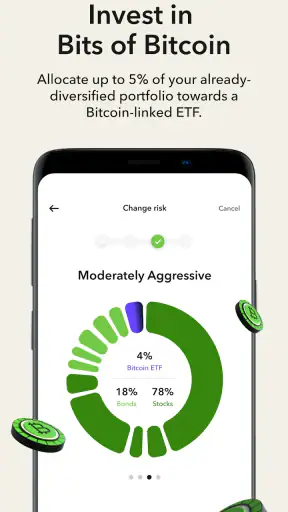
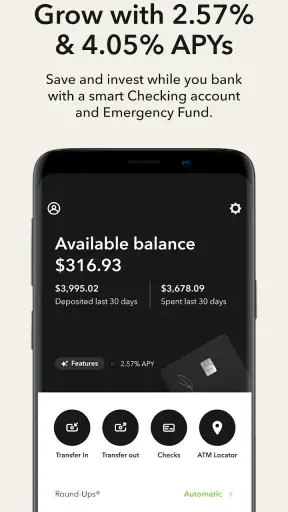
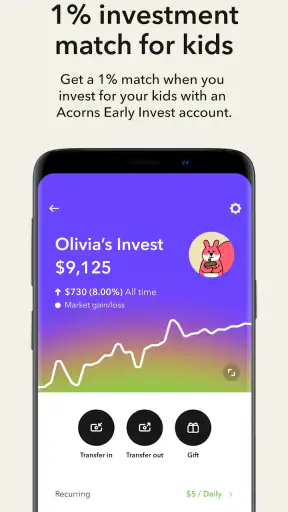
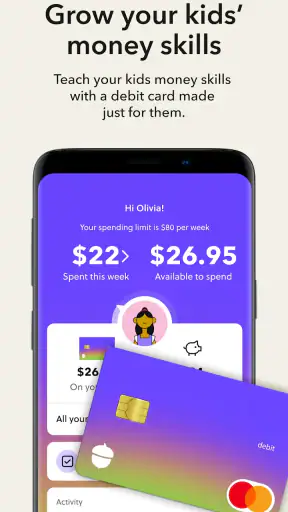
I judge an investing app not only by what it lets me do, but by whether I can understand what is happening without turning every spare moment into a research project. That is the appeal of Acorns: Invest For Your Future: it makes small, routine contributions feel more approachable. Still, easy setup should not be confused with effortless financial progress. The useful question is whether its hands-off style matches your habits, goals, and comfort with risk.
What the hands-off approach changes
Acorns is a finance app from developer Acorns, and its central idea is to make investing fit around everyday spending. Rather than asking me to choose individual investments each time I open it, it connects small contributions with a preset investing approach. That can lower the mental hurdle for someone who has been putting off getting started, though it also means the experience is less suitable for people who want to make every investment decision themselves.
The app is free to download, but I would not treat that as proof that every investing service or account option has no cost. Before committing money, I would check the current terms and consider how any charges fit the amount I expect to invest. This matters especially when contributions are small: a fee can take up a more noticeable share of a modest balance than of a larger one.
Speed expectations and everyday use
Acorns is designed around gradual investing, so I would not expect a quick action in the app to produce an immediate investment result. Linking an account, setting preferences, and reviewing choices are distinct steps, and financial transactions can involve processes beyond the app itself. I find it more helpful to think of the app as a routine-setting tool than as a place to chase fast market moves.
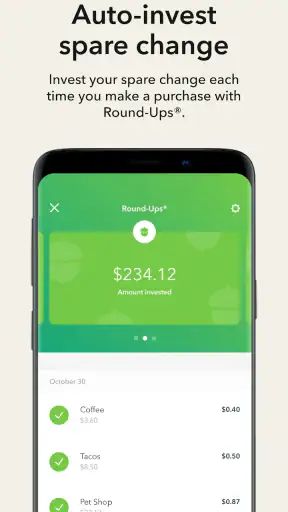
For example, imagine someone who buys lunch and a few household items during a normal week. Round-Ups can turn eligible purchases into a prompt to invest spare change, while recurring deposits can make the habit more deliberate. The practical trade-off is that frequent small contributions still come from a real budget. I would check the linked account and spending pattern before enabling an approach that might collect more than expected.
When activity gets heavier
The experience can involve more than passively watching a balance. A person might review a portfolio, read a lesson, consider an IRA, and adjust a contribution plan in one sitting. Those are different kinds of tasks, and I would approach them in order: understand the account and risk choices first, then decide whether the extra tools fit a specific goal. More activity is not automatically better investing.
A useful habit is to review contributions against actual cash flow rather than changing them in response to every market headline. If income varies from week to week, a fixed recurring amount may deserve more attention than Round-Ups alone. If the linked account is used for shared household spending, I would also make sure the person funding investments understands how those small amounts are being gathered.
Reliability and the role of routine
With any finance app, reliability is not just about whether screens open; it is also about keeping track of what has been arranged and checking that activity makes sense. I would make a periodic review part of the routine instead of assuming that a set-and-forget setup needs no attention. That is particularly sensible when bank connections or personal circumstances change.
Acorns has an average rating of 4.7 from around 387,000 ratings, with roughly 77,000 written reviews, and more than 10 million installs. Those figures suggest that many people have tried it, but they do not tell me whether its investing style suits an individual account. I would use the app’s own account information and terms to make decisions, not popularity alone.
Device fit and financial fit
The app is rated for Everyone and requires iOS or Android version 10 or later. Its current version is 4.183.0, and it has been available since October 7, 2014. Those details help with a basic compatibility check, but they cannot tell me how smoothly it will feel on every device or with every network connection. If I were relying on it for regular account checks, I would keep the operating system current where possible and make sure I can access important account information through the appropriate channels.
People who want a self-directed brokerage, detailed control over individual securities, or a highly tailored portfolio may prefer a conventional investment platform. Someone who mainly wants to budget may be better served by a budgeting tool that focuses on spending plans rather than investing. Acorns sits in a different lane: it tries to connect small, repeatable contributions with a managed investing experience.
Have you ever felt like investing is a mysterious world, only accessible to those with fat wallets and spreadsheets for breakfast? Well, let me introduce you to Acorns: Invest For Your Future, an app that aims to turn this notion on its head. I've been tinkering with it for a while, and here's my two cents—or should I say, my few acorns—on how it works.
Getting Started with Acorns
So, diving right into the app, the first thing you'll notice is its sleek and user-friendly interface. Setting up an account is as easy as pie. You just need to link a bank account, and voilà, you're good to go! The app cleverly rounds up your everyday purchases to the nearest dollar and invests the spare change into a diversified portfolio. It’s like a digital piggy bank that invests!
The sign-up process is straightforward, with clear prompts guiding you through each step. You’ll answer a few questions about your financial goals and risk tolerance. And don’t worry, the questions are more like having a casual chat than taking a complex financial exam.
Features That Stand Out
One of the features that really caught my attention is the "Found Money" program. Imagine getting free investment boosts just by shopping with certain brands. It’s like getting a little reward for indulging in some retail therapy. Who doesn’t love that?
Another nifty feature is the "Round-Ups". It might seem trivial to invest your spare change, but trust me, those pennies add up. Over time, you’ll find yourself pleasantly surprised at the growth of your investment. Plus, you can supercharge your investments by making one-time or recurring deposits.
Learning and Growing
Now, if you're like me and still learning the ropes of investing, Acorns has got your back. The app offers educational content tailored to your level of financial literacy. You’ll find easy-to-digest articles and videos that explain investing basics without the jargon. It’s like having a friendly financial advisor in your pocket.
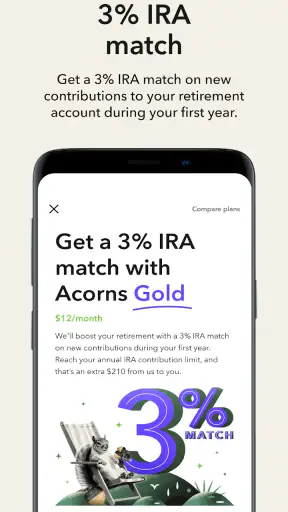
Moreover, Acorns provides a nifty feature called "Acorns Later," which helps you set up an IRA effortlessly. Planning for retirement might seem daunting, but this feature simplifies the process, making it accessible and straightforward.
Is Acorns for Everyone?
Now, let’s talk about who this app is really for. If you’re someone who wants to dip their toes into the world of investing without diving into complicated financial markets, Acorns: Invest For Your Future is perfect for you. It's particularly great for millennials and Gen Z folks who are just starting out on their financial journey.
However, if you're a seasoned investor looking for advanced trading options or customization, you might find Acorns a bit limiting. The portfolios are predefined, and while they're diversified, you don't have control over individual stock picks.
Wrapping It Up
So, what’s the final verdict? Acorns is an app that makes investing approachable and fun. It's a great tool for novices and anyone who wants to grow their savings without a hefty initial investment. The app's seamless integration of everyday spending and investing makes it a standout in the crowded fintech space.
Whether you're saving for a rainy day or planning for a golden retirement, Acorns has something to offer. So, why not give it a whirl? It might just help you turn those acorns into mighty oaks!
Making the routine work for your budget
A small, non-obvious choice is whether to rely on Round-Ups as the main contribution method or treat them as a supplement. I would not assume spare change alone will match a target; it depends on how often I use the linked card and the size of purchases. A more practical workflow is to choose a contribution I can sustain, then let Round-Ups add a variable extra rather than counting on them for a deadline-driven goal.
For someone with irregular income, that distinction matters. I would start conservatively, observe how the linked spending affects the account, and avoid setting a recurring amount that competes with rent, bills, or an emergency cushion. The convenience is real, but automation can make money feel less visible. A quick monthly check can turn an invisible drain into a deliberate choice.
Small rewards still need a plan
Found Money may make a purchase feel more rewarding, but I would not buy something solely to get an investment boost. The useful test is whether I would have made that purchase anyway and whether it fits my budget. A reward attached to spending is not the same as saving the full purchase amount, so it works best as a side benefit rather than a reason to shop.
Likewise, the educational material can help a beginner get familiar with basic concepts, but I would treat it as a starting point, not a substitute for understanding the account choices and risks. Before adding money, I would be able to explain in plain language what goal I am investing for, how much fluctuation I can tolerate, and when I might need the money. If those answers are unclear, slowing down is more useful than pressing through setup just because the prompts feel simple.
Choosing between Acorns and other tools
Compared with picking stocks through a self-directed brokerage, Acorns asks less of me day to day, but gives up some control. Compared with a savings account, investing introduces the possibility of market movement, so it is not an interchangeable place to hold money I need immediately. And compared with a budget app, its main job is not to map every bill or spending category. I would choose based on the job I need done, rather than expecting one app to cover all three.
That makes it most compelling for a beginner who wants a repeatable investing habit and is comfortable with a predefined portfolio. It is less compelling for someone who already invests confidently, wants to select particular securities, or needs tight control over when every dollar moves. It may also be a poor fit if even small automated transfers would make the monthly budget feel unpredictable.
What I would check before relying on it
Before making Acorns part of my routine, I would confirm that the linked account is the right one, read the current account terms, and understand how contributions are scheduled. I would also decide what a comfortable amount looks like before turning on automatic activity. These checks are especially useful if several people share a bank account or if card purchases vary widely from week to week.
If the app seems slow or a screen does not refresh as expected, I would avoid repeating a financial action immediately. I would first check the account activity and transaction status, then try again only when I understand whether the earlier action went through. That cautious approach is worthwhile with any investment service: a brief wait is preferable to accidentally duplicating a contribution. I would also keep a separate record of my goal and planned contribution so a device issue does not become the only thing standing between me and knowing what I intended.
My performance verdict
Acorns is built for a steady, low-effort rhythm, not rapid-fire trading. I find that a sensible match for its round-up concept: the value is in making investing a repeatable habit, not in opening the app constantly. Its setup and guided choices can make a first step feel less intimidating, while the predefined approach and dependence on connected spending will not suit every financial style.
My recommendation is conditional but positive. If you want an approachable way to begin investing, have room in your budget for contributions, and are happy to give up individual investment selection, Acorns is worth considering. If you need instant access to every dollar, prefer a cash-focused savings tool, or want hands-on control, I would choose a different option. The best outcome comes from treating automation as a reminder to invest thoughtfully—not as a reason to stop paying attention.
4.7
77.07K Reviews
Pros
- Easy-to-use interface for beginners
- Automatic round-ups help save effortlessly
- Diverse investment portfolios available
- Educational content for financial literacy
- Low minimum investment required
Cons
- Monthly fees can add up over time
- Limited control over investment choices
- No tax-advantaged accounts available
- Requires bank account linking
- Customer support can be slow


